The Price of Oil Is More Than a Barrel: How Tanker Availability Shapes the Economics of Global Energy
Oil is priced in commodity markets, but its delivered value depends on ships, routes, insurance and time. When transport capacity becomes scarce, the economics of the barrel change.
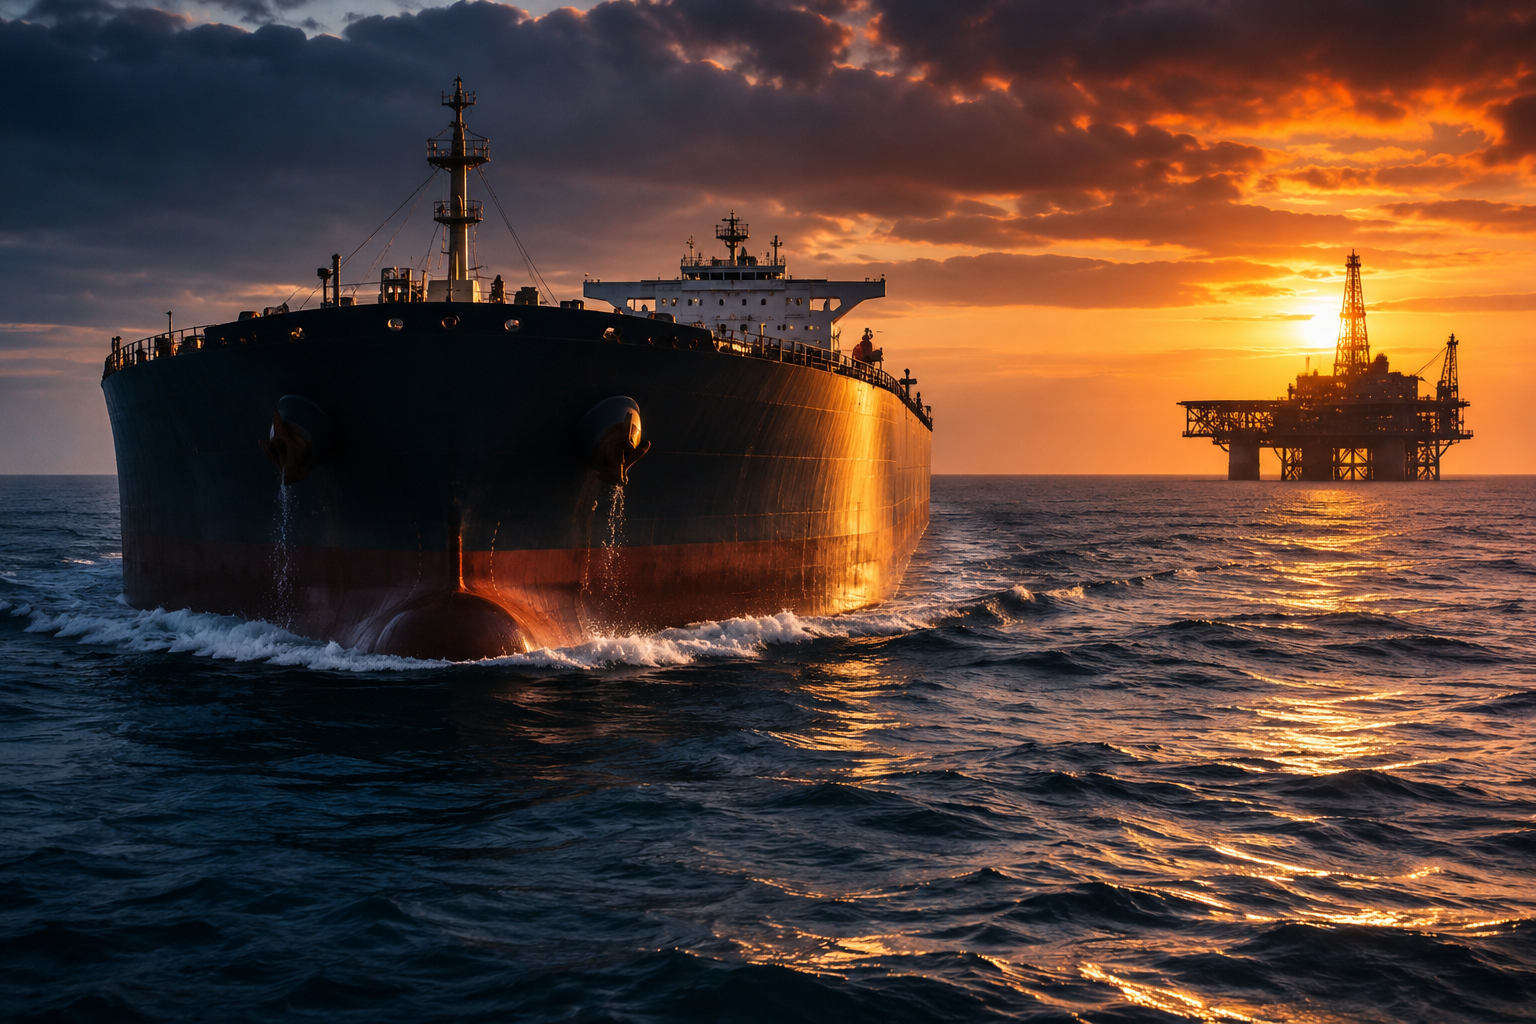
Oil is often discussed as though it were a commodity that moves frictionlessly from producer to consumer. In reality, a barrel of crude has to be loaded, insured, transported, discharged and processed. The vessel carrying it is not a secondary detail. It is part of the supply chain that gives the commodity its delivered value.
The availability of tankers does not independently set the international benchmark price of oil. Brent and WTI are shaped by a much wider interaction of expected supply, demand, inventories, quality differences, futures markets and geopolitical risk. Yet tanker availability can materially affect freight rates, regional price differentials, the delivered cost of crude and, in periods of severe disruption, the effective supply reaching particular markets.
This distinction is central to understanding modern energy markets: the price of oil at the loading terminal and the cost of oil delivered to a refinery are not necessarily the same thing.
1. The barrel has two markets: the commodity and its transportation
Crude oil is traded through physical contracts and financial benchmarks. But the physical trade requires maritime capacity, especially for long-distance movements between the Middle East, West Africa, the Americas, Europe and Asia. The tanker market supplies that capacity through a combination of spot fixtures, time charters, contracts of affreightment and longer-term commercial arrangements.
When vessels are plentiful and positioned near loading areas, charterers have more choice. When ships are scarce, committed elsewhere, delayed or unwilling to enter a high-risk area, charterers compete for a smaller pool of prompt tonnage. Freight can rise even if the volume of crude available at the export terminal has not changed.
The delivered price is therefore a logistics outcome as well as a commodity-market outcome. A refinery evaluating two crude grades must consider not only the quoted price and quality but also the cost, timing and reliability of delivery.
2. The effective fleet is smaller than the fleet on paper
One of the most important distinctions in tanker economics is the difference between the total number of ships in existence and the number of ships commercially available for a particular cargo, route and date.
A vessel may be physically afloat but unavailable to the mainstream market because it is:
- trading under sanctions restrictions or subject to counterparty and port-access limitations;
- committed to a time charter or another cargo programme;
- waiting at anchor, delayed by congestion or caught in a disrupted trading area;
- undergoing dry-docking, repairs, inspection or other maintenance;
- unable or unwilling to enter a high-risk area because of insurance, crew-safety or owner policy;
- poorly positioned relative to the next loading area, making ballast time and cost uneconomic.
This means a geopolitical event can tighten the prompt tanker market without physically removing a single ship from the world fleet. The effective supply of compliant, insured and suitably positioned tonnage can contract sharply even when the global fleet count is unchanged.
It is also important not to treat all vessels as interchangeable. A VLCC, Suezmax and Aframax have different cargo capacities, port constraints, draft requirements, route economics and suitability for particular terminals. A shortage of one vessel class cannot always be solved by deploying another.
3. Freight rates influence the delivered price, not mechanically the benchmark
Consider a simplified example. The crude loading price remains at $75 per barrel in both cases. The only change is the cost of moving the cargo.
| Illustrative cost per barrel | Normal conditions | Disrupted conditions |
|---|---|---|
| Crude at loading terminal | $75.00 | $75.00 |
| Ocean freight | $2.00 | $6.00 |
| Insurance and other logistics | $0.50 | $2.00 |
| Indicative delivered cost | $77.50 | $83.00 |
In this hypothetical example, the delivered cost rises by $5.50 per barrel even though the loading price is unchanged. The numbers are illustrative rather than current market quotations; actual freight per barrel depends on vessel size, cargo quantity, route, port costs, charter terms, speed, fuel and the prevailing freight market.
A refinery may absorb some of the increase, negotiate a lower FOB price, switch grades or suppliers, or pass the cost through into product prices. If alternative crude is available from a closer or safer source, the buyer may change its sourcing strategy. These adjustments can widen or narrow regional crude differentials.
In a sufficiently large disruption, higher freight and reduced transport capacity can contribute to a wider physical supply squeeze. But it would be inaccurate to say that a rise in tanker rates automatically produces an equal rise in Brent. The relationship is mediated by inventories, alternative routes, spare production, refinery demand and the ability of buyers to substitute suppliers.
4. Tonne-miles: why the distance travelled can matter as much as the barrels
Tanker demand is not simply a function of how many barrels are shipped. It is also a function of how far those barrels travel. The industry describes this relationship through tonne-miles: cargo quantity multiplied by distance.
Suppose an Asian refinery replaces a cargo previously sourced from the Persian Gulf with a cargo from the Atlantic Basin. The volume of oil bought may remain the same, but the voyage becomes longer. The tanker is occupied for more days and cannot complete as many voyages within the same period.
That change increases the demand for vessel-days even though the number of barrels consumed has not increased. It is one reason a geopolitical rerouting can tighten tanker markets during a period when global oil demand is weak or falling.
Longer voyages also create knock-on effects. Ships may arrive in different regions than expected, ballast legs may lengthen, port congestion can build and the availability of prompt vessels near traditional loading areas may decline. A seemingly local disruption can therefore influence freight markets across several basins.
5. The Strait of Hormuz: a case study in effective shipping capacity
The Strait of Hormuz illustrates how the physical security of a route can alter the effective supply of ships. When the passage is perceived as unsafe, owners, charterers and insurers reassess the risk of transit. Some voyages may be delayed, some vessels may wait outside the area, and others may be redirected or excluded by contractual and insurance restrictions.
The impact is not limited to the cargoes that fail to move. A ship waiting for instructions or held outside a loading area is a ship that cannot complete another voyage. A vessel that takes a longer alternative route consumes more vessel-days. A ship that is technically available but cannot obtain acceptable cover may be commercially unusable for a particular charterer.
The same logic applies to other maritime chokepoints and conflict-affected corridors. Risk can reduce effective capacity through waiting time, rerouting, insurance cost and operational caution long before the global fleet itself changes in size.
6. Insurance, sanctions and compliance are part of vessel availability
In modern tanker markets, availability is not purely a question of steel and deadweight. A ship must also be acceptable to the relevant charterer, cargo owner, bank, terminal, port state and insurer. Sanctions screening, ownership transparency, classification status, flag, documentation and insurance can determine whether a vessel can participate in a trade.
Restrictions on vessels carrying sanctioned oil may reduce the pool of ships that mainstream buyers and counterparties are prepared to use. At the same time, opaque or older tonnage may continue to trade through alternative channels. This creates a segmented market: the headline global fleet is not the same as the pool of vessels accessible to every buyer.
For owners, compliance and transparent operations can be a commercial advantage, particularly when counterparties are risk-sensitive. For charterers, the cheapest nominal freight may not be the cheapest total solution if it introduces unacceptable legal, insurance, safety or reputational exposure.
7. The feedback loop between oil and shipping markets
The relationship between oil and shipping is circular rather than one-directional.
- Geopolitical disruption, sanctions or congestion reduce the number of vessels available for a route.
- Charterers compete for the remaining suitable ships, lifting freight and sometimes insurance costs.
- Higher transport costs change delivered crude economics and the relative attractiveness of suppliers.
- Buyers redirect cargoes, potentially increasing voyage distances and tonne-mile demand.
- Longer voyages and waiting time absorb more vessel-days, tightening prompt availability further.
- Higher delivered costs can eventually influence refinery margins, product prices, inventories and demand.
The cycle is not inevitable or unlimited. High freight rates can encourage owners to reposition ships, prompt buyers to draw inventories, stimulate alternative supply routes or reduce marginal cargo movements. But when the fleet is already highly utilised and route alternatives are limited, the adjustment can be slow and volatile.
8. What shipowners, traders and refiners should monitor
For market participants, the most useful indicators are not limited to the headline oil price or a single freight index. A more complete assessment should combine:
- Prompt vessel lists: the number of suitable ships open in the relevant loading range and time window.
- Ballast positioning: where ships are located, how long they will take to reach load ports and whether repositioning is economic.
- Voyage duration and waiting time: congestion, security delays, speed changes and port restrictions.
- Freight benchmarks and fixtures: route-specific assessments, actual concluded business and the difference between quoted and fixed rates.
- Insurance conditions: war-risk premiums, exclusions, deductibles and the availability of acceptable cover.
- Sanctions and compliance: vessel, owner, flag, cargo and counterparty restrictions.
- Inventory and refinery data: stock cover, refinery runs, product cracks and the availability of alternative grades.
- Route substitution: changes in sourcing patterns and the resulting shift in tonne-mile demand.
No single indicator gives a complete picture. A freight index can rise because of longer voyages or congestion even when cargo volumes are flat. Conversely, a large fleet can coexist with a shortage of prompt, compliant vessels in a particular basin.
9. Implications for investment and commercial strategy
For shipowners, the value of a tanker is influenced by more than deadweight, age and technical condition. Its earning potential depends on the routes it can trade, its compliance profile, its position relative to cargo demand, the balance of vessel supply and the amount of time it spends earning freight rather than waiting or repositioning.
For oil traders and refiners, securing a cargo is only part of procurement. The buyer must also secure a vessel, acceptable insurance, a workable delivery window and a route that makes economic sense. In a constrained market, the ability to secure reliable transportation can be a competitive advantage in its own right.
For investors, extreme freight earnings should not automatically be extrapolated. A durable improvement in security can release delayed vessels, shorten voyages and reduce insurance costs. Freight markets can correct quickly once the effective fleet expands, even if the physical number of ships has not changed.
Conclusion: the commodity is only as accessible as its route
The global oil market cannot be understood solely through production forecasts, inventories and consumption. Maritime transportation is the mechanism that connects supply with demand across continents. When tanker availability contracts, the effect is visible in freight rates, delivery schedules, regional price differences and the cost of supplying refineries.
The essential distinction is between the quoted price of a barrel and the economic cost of obtaining that barrel at the point of consumption. The former is shaped by the global commodity market; the latter also depends on vessels, routes, insurance, time and operational risk.
This does not mean that tankers set the price of Brent or that freight alone explains every oil-price movement. It means that shipping capacity is an essential transmission mechanism between geopolitical events and the physical energy market — and one that deserves far greater attention in any serious analysis of global oil economics.
Further reading
- International Energy Agency, Oil Market Report — October 2026. Market context on supply disruption, freight costs, inventories and refining.
- Baltic Exchange. Freight-market benchmarks and tanker market information.
- Clarksons. Shipping market research, fleet data and vessel-market analysis.
- International Maritime Organization. Maritime safety, pollution prevention and regulatory information.
Editorial note: The delivered-cost table is a hypothetical illustration, not a current freight quotation. This article is intended as market analysis and does not constitute investment advice.